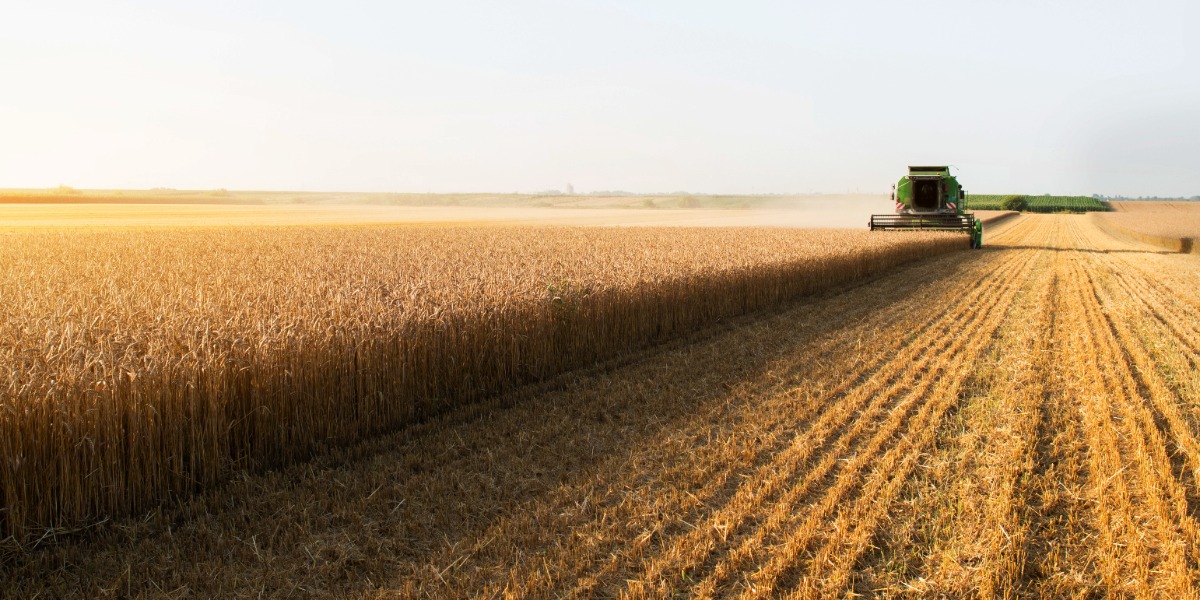
Global wheat prices are climbing, but not because the world is running short of grain. New Rabobank research says disruption to trade routes is driving the market, and the same pressures are pushing up costs for Australian growers.
The report, From Hormuz to El Niño, says rising freight and insurance costs and broader geopolitical instability are reshaping both wheat prices and production costs.
“The world is not short of wheat,” said RaboResearch senior grains and oilseeds analyst Vitor Pistoia.
“The challenge is getting grain to buyers reliably and at an acceptable cost.”
Mr Pistoia said futures markets point to stronger prices into 2027. In early October, prices into mid-2027 were pointing toward AUD 365 to AUD 370 a tonne, compared with AUD 325 to AUD 335 a tonne three months earlier.
Australian port prices are expected to broadly track international markets. The report cautions that some of the current premium could disappear if conditions improve.
“If we see a ceasefire, a new export agreement or a restoration of Black Sea export capacity, part of the current risk premium could unwind relatively quickly,” he said.
Russia and Ukraine harvested strong wheat crops in 2026. Disruption to export infrastructure and shipping routes is expected to have cut their exports by about seven million tonnes between July and September. That is nearly 50 per cent below normal and equal to about four per cent of annual global wheat trade.
“Disruption to ports, vessels and shipping routes has reduced export reliability and increased freight and insurance costs,” Mr Pistoia said.
“Grain is still being produced. The challenge is moving it.”
The report says Australia could gain an edge in Asian markets, because northern hemisphere exporters face longer and potentially more disrupted shipping routes.
“Indicative sailing times to Indonesia are around eight days from Australia’s west coast and about 10 days from the east coast,” he said.
“Grain shipped from France or the Black Sea via the Cape of Good Hope can take around 40 days.”
The benefit to growers may be partly offset by higher input and freight costs.
“For Australian growers, stronger grain prices are welcome, but higher input costs continue to erode margins,” Mr Pistoia said.
“In some cases, production costs have risen more sharply than wheat prices.”
Diesel typically makes up around four to six per cent of on-paddock operating costs. Fertiliser is the bigger risk, because it is frequently the largest variable cost in wheat production and buying decisions often have to be made months ahead.
The report also points to the prospect of El Niño conditions emerging in 2027. The impact on the 2026/27 crop is expected to be limited, but the risk is larger for eastern Australian grain production in 2027/28 if lower winter rainfall cuts yields.
“Positive margins can still be achieved during periods of elevated costs, as we have seen previously,” Mr Pistoia said.
“The opportunities are there, but disciplined risk management will be critical.”
Something going on in your part of the New England people should know about? Let us know by emailing newsdesk@netimes.com.au